You just found out your house sits in a FEMA flood zone, and now you’re wondering what that means for selling a house in a flood zone in Arizona. It doesn’t mean your house is unsellable. It does mean a few extra steps, an insurance conversation for any financed buyer, and a disclosure duty you need to get right.
Yes, you can sell a house in an Arizona flood zone. A flood zone designation narrows your buyer pool and can slow down a financed sale, but it doesn’t block a sale outright. A cash sale sidesteps most of the friction entirely. For the full picture on speed, pricing, and process, see our guide to selling your house fast for cash in Arizona.
Here’s what actually changes when a flood zone shows up on your property:
- Most of the Phoenix metro sits outside FEMA’s Special Flood Hazard Areas, but parcels near washes, canals, and the older river corridors often don’t.
- A financed buyer in a high-risk zone will be required to carry flood insurance, and that premium changes their monthly payment math, not just yours.
- Arizona’s Seller’s Property Disclosure Statement (SPDS) treats flood risk as a material fact, separate from the narrow flood affidavit statute that applies mainly to unincorporated land sales.
- Standard homeowners insurance never covers flood damage, so a buyer’s lender will raise the flood question before closing, not after.
- We buy homes in flood zones as-is, at our own risk, without asking you to shop for flood insurance quotes or wait on a lender’s flood determination.
Does a Flood Zone Designation Stop You From Selling a House in Arizona?
No, a flood zone designation does not stop you from selling a house in Arizona. It changes who can easily buy it and how, not whether you can sell it.
A flood zone mainly affects buyers who need a mortgage. Federally backed loans in a high-risk zone require flood insurance before closing, and lenders often ask for an updated elevation certificate or flood determination during underwriting. That can slow an appraisal, extend a financing contingency, and shrink your pool of interested, qualified buyers. It rarely stops a sale from happening. A local direct buyer who pays cash and buys with their own funds isn’t waiting on a lender’s flood determination or an insurance quote, so the zone designation has far less effect on that path.
How to Check If Your Arizona House Is in a FEMA Flood Zone
You can check your house’s flood zone status for free through FEMA flood maps by searching for information about your property.
The tool pulls the current Flood Insurance Rate Map (FIRM) for your parcel and returns a zone letter. Your county flood control district and city floodplain administrator keep the same maps on file and can confirm the reading if the online result looks unclear or your property sits near a zone boundary. If you’re refinancing or under contract, your lender will also run its own flood determination, which is the version that actually governs your insurance requirement.
Does Being in a Flood Zone Mean Your Arizona House Has Flooded Before?
Not necessarily. A FEMA flood zone designation describes the mapped flood hazard for an area, not proof that your specific house has flooded in the past. A property can be located in a higher-risk zone without having experienced documented flood damage, while a property outside a high-risk zone may still have a history of flooding from drainage problems, storm runoff, or localized events.
This distinction matters when you’re selling a house in a flood zone in Arizona. Buyers may ask whether the home has ever flooded, whether repairs were required, and whether the property has received insurance claims or federal disaster assistance. A flood zone designation alone cannot answer those questions.
Before listing your house, gather any records you have about previous flooding, water intrusion, repairs, drainage work, or insurance claims. If you don’t know whether the property has experienced flooding, don’t guess. Tell your agent or buyer what you know and what you haven’t been able to verify.
You should also distinguish between the FEMA flood zone and local drainage conditions. Arizona properties can experience stormwater runoff or localized flooding even when they aren’t in a FEMA-designated high-risk zone. Check relevant county or city flood-control information when assessing your property’s situation.
What Each FEMA Flood Zone Designation Means for Sellers
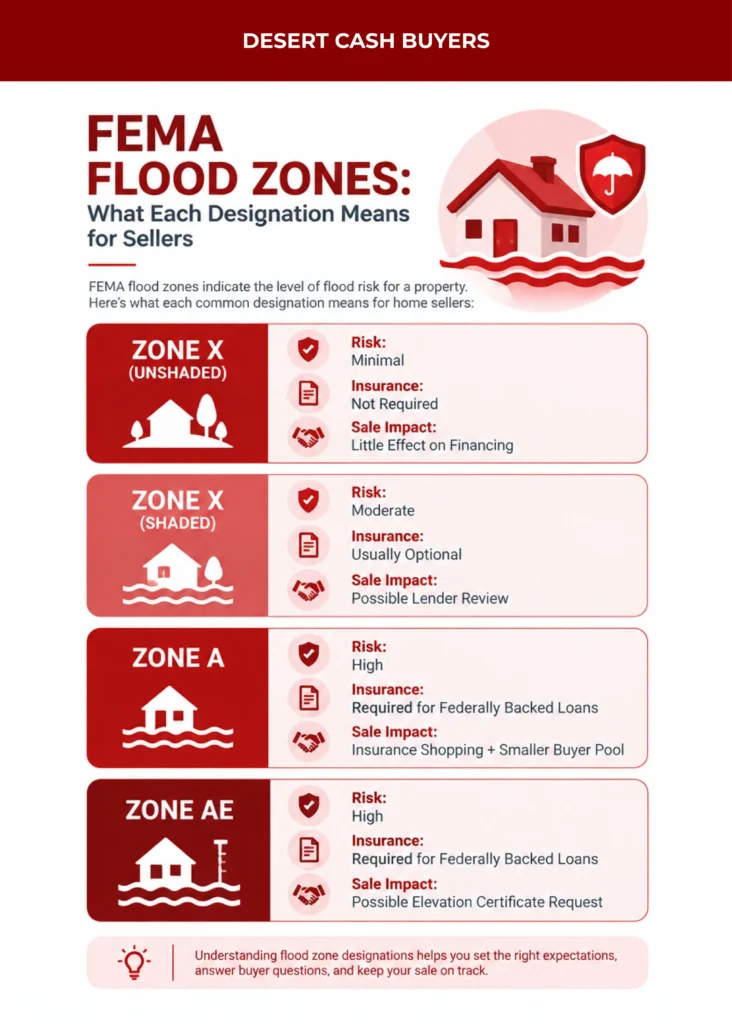
Zone X means minimal flood risk and no federal insurance requirement. Zone A and Zone AE mean your house sits in a Special Flood Hazard Area, where flood insurance is required for federally backed loans.
| FEMA Zone | Risk Level | Insurance Requirement | What It Means for Your Sale |
| Zone X (unshaded) | Minimal risk, outside the 500-year floodplain | Not required, optional coverage available | No practical effect on financing or disclosure beyond standard SPDS honesty |
| Zone X (shaded) | Moderate risk, inside the 500-year floodplain | Not federally required, often recommended | Some lenders flag it; usually a minor underwriting note |
| Zone A | High risk, Special Flood Hazard Area, no base flood elevation published | Required for federally backed loans | Narrows buyer pool, adds an insurance shopping step for financed buyers |
| Zone AE | High risk, Special Flood Hazard Area with a published base flood elevation | Required for federally backed loans | Same as Zone A, plus a possible elevation certificate request from the lender |
Zone X: Minimal Flood Risk
Zone X covers most of the developed Phoenix metro. If your house is here, a flood zone designation is essentially a non-issue for your sale. You’ll still see the question on the SPDS, and you should answer it accurately, but it won’t change financing, insurance, or buyer interest in any meaningful way.
Zone A and Zone AE: Special Flood Hazard Areas
Properties in Zone A or Zone AE are inside what FEMA calls a Special Flood Hazard Area, the area with a 1 percent annual chance of flooding, sometimes called the 100-year floodplain. This is the designation that triggers a mandatory flood insurance purchase for any loan backed by a federal agency or bought by Fannie Mae or Freddie Mac.
How Flood Insurance Costs Can Affect Your Arizona Home Sale
Flood insurance can affect a buyer’s budget even when the property is otherwise attractive and qualifies for financing. The lender’s insurance requirement is only part of the calculation. Buyers may also compare the annual premium, deductible, coverage limits, and exclusions before deciding whether the home fits their budget.
Flood insurance pricing depends on property-specific factors, including the property’s location, flood risk, building characteristics, coverage selected, and the insurer’s underwriting rules. You shouldn’t assume every house in Zone AE has the same premium or that every property in Zone X will have an inexpensive policy.
For sellers, the practical issue is affordability. A buyer who qualifies for the mortgage payment may still need to account for flood insurance and other property expenses. That can affect the offer amount, the buyer’s preferred closing timeline, or whether they proceed with the purchase.
If you already carry flood insurance, keep your policy declarations page and relevant claim information available. A buyer may ask about existing coverage, and their lender or insurance agent will determine what coverage they need for the new loan and property.
Don’t promise a buyer that flood insurance will cost a specific amount. Encourage them to obtain a property-specific quote early, especially if financing is involved. Getting that information before the end of the transaction can help prevent surprises during underwriting.
What Arizona Law Actually Requires You to Disclose About Flood Risk
Arizona law requires you to disclose material facts about flood risk, but the specific flood affidavit statute applies narrowly, not to most in-city home sales. A.R.S. § 33-422 requires a written affidavit of disclosure, including flood-related items, but only from a seller of five or fewer parcels of unsubdivided land in an unincorporated county area, and any later reseller of that same parcel. A typical resale inside Scottsdale, Phoenix, Chandler, Mesa, Tempe, Gilbert, or Cave Creek generally falls outside that narrow trigger.
What actually governs most sales is the broader duty Arizona courts have recognized: a seller must disclose material facts that affect a property’s value or desirability, and staying silent about a known problem can carry the same legal weight as an outright misrepresentation. Flood history and a known Special Flood Hazard Area designation are the kind of material facts this duty covers. The standard tool for meeting that duty is the Seller’s Property Disclosure Statement (SPDS), where flood-related questions should be answered completely and honestly. Confirm the current SPDS language and any local flood-affidavit requirement with your title company or an attorney before you sign, since disclosure forms and statutes can be updated.
How a Flood Zone Affects a Buyer’s Mortgage, Insurance, and Appraisal
A flood zone adds a mandatory insurance requirement and an extra underwriting step for any buyer using a federally backed loan.
Why Federally Backed Loans Require Flood Insurance in a Special Flood Hazard Area
Federal law requires flood insurance on any home in a Special Flood Hazard Area that’s financed with a federally backed or federally regulated mortgage. Coverage runs through the National Flood Insurance Program (NFIP), which the Arizona Department of Water Resources coordinates locally as the state’s NFIP liaison. Because NFIP authorization is renewed by Congress periodically rather than made permanent, confirm the program’s current status before you rely on a specific timeline for a buyer’s insurance approval.
A lender’s appraiser will also note the flood zone on the appraisal, and an underwriter may ask for an elevation certificate to confirm how far the structure sits above the base flood elevation. None of this is unusual, but it adds steps and time to a financed transaction that a cash sale, paid at closing through a licensed, independent Arizona title company with funds held in escrow, simply doesn’t need.
How Much Longer a Flood-Zone Sale Takes With a Traditional Listing
A cash sale to Desert Cash Buyers closes in 7 to 14 days from accepted offer regardless of flood zone status, with our fastest close on record at 3 days. A financed sale in a flood zone typically needs extra time for flood insurance shopping and lender review, on top of a standard escrow.
The table below is an illustrative example scenario to show where that extra time tends to show up. It is not a published market statistic. Confirm current local timelines with your lender, agent, or title company for your specific situation.
| Step | Standard Financed Sale | Financed Sale in a Flood Zone | Cash Sale With Desert Cash Buyers |
| Offer to acceptance | Same day to a few days | Same day to a few days | About 15 minutes to a same-day offer |
| Flood determination and insurance shopping | Not applicable | Adds roughly 1 to 3 weeks | Not needed; we buy as-is |
| Appraisal and underwriting | 2 to 4 weeks | 2 to 4 weeks, plus flood review | Not applicable |
| Closing | 30 to 45 days typical, example range | 45 to 60 days typical, example range | 7 to 14 days, fastest on record 3 days |
Does Being in a Flood Zone Lower What Your House Is Worth?
Being in a flood zone can reduce your buyer pool more than it reduces a fair offer, and the two aren’t the same thing. A smaller pool of interested, qualified buyers can soften negotiating leverage in a traditional listing, especially if a deal falls through late in escrow over an insurance quote or an elevation certificate.
A direct cash buyer prices from comparable sales, the property’s actual condition, and repair costs- the same offer math behind every cash offer we make. Ask any buyer, cash or financed, to show you the comps and the reasoning behind a number. That’s genuinely useful advice whether or not you sell to us, and it protects you from a lowball offer dressed up as a flood-risk discount.
Your Options for Selling a House in a Flood Zone in Arizona
You have three realistic paths once you know your zone designation: list traditionally with full disclosure, mitigate the risk before you list, or sell as-is to a local cash buyer.
- List traditionally with full disclosure. Works well if your house is in good condition, you have time, and you want to reach the widest possible buyer pool, including financed buyers who plan to insure and stay.
- Elevate or mitigate before you list. Flood vents, grading changes, or an elevation certificate showing the structure sits above the base flood elevation can sometimes move a Zone AE property out of the highest-risk insurance tier. This takes time and money upfront.
- Sell as-is to a local cash buyer. Removes the insurance-shopping and appraisal bottleneck entirely, since there’s no lender flood determination to wait on.
Option 3: Sell As-Is to a Local Cash Buyer
We evaluate your property by phone or with a single private visit, never an open-house parade, and we make a cash offer in about 15 minutes with the comps and repair math explained. See exactly how the process works on our How It Works page, or start with a no-obligation cash offer today.
When Listing Traditionally Still Makes Sense, Even in a Flood Zone
If your house is in good condition, sits in a lower-risk zone like Zone X, and you have no deadline, listing with an agent may net you more over time. A cash sale is the right tool for speed and certainty, not for topping the market. If your situation is less about flood risk and more about a hard-to-sell location generally, our page on selling your house fast in a bad location in Arizona covers the broader picture.
Frequently Asked Questions: Selling a House in a Flood Zone in Arizona
Do I have to tell buyers my house is in a flood zone in Arizona?
Yes. Flood risk is a material fact under Arizona’s disclosure duty, and it belongs on your Seller’s Property Disclosure Statement even when the narrower flood-affidavit statute doesn’t apply to your specific sale.
Can I sell my house for cash if it’s in a FEMA flood zone?
Yes. We buy homes throughout the Phoenix metro, including Phoenix, regardless of flood zone status, and the zone designation doesn’t change our offer math beyond how it factors into repair and risk assumptions the same way any property condition would.
Does flood insurance transfer to the new owner when I sell?
No. Flood insurance policies don’t transfer automatically. A financed buyer purchases their own policy before closing if the lender requires it. A cash sale to a direct buyer skips this step entirely, since we don’t finance the purchase with a federally backed loan.
Will a flood zone designation show up on the appraisal?
Yes, for a financed sale. The appraiser notes the FEMA zone, and the lender’s underwriter reviews it as part of approving the loan. This step doesn’t apply to a cash purchase, since there’s no appraisal contingency tied to lender financing.
Is Zone AE worse than Zone A for selling my house?
Not necessarily worse, just more specific. Zone AE includes a published base flood elevation, which actually gives a buyer’s lender clearer data to work with than Zone A, where no base flood elevation has been established yet. Either zone triggers the same mandatory insurance requirement for a federally backed loan.
Selling a House in a Flood Zone Arizona: Your Next Steps
Selling a house in a flood zone in Arizona may require extra attention to flood disclosures, insurance requirements, and buyer financing, but it doesn’t mean your property is unsellable. Check your FEMA zone, disclose known flood risks honestly, and weigh whether a traditional listing or a cash sale makes more sense for your timeline and situation.
If you’d rather avoid the lender’s flood determination, insurance shopping, and potential appraisal delays, get your free cash offer from us. We purchase Arizona homes as-is, including properties in flood zones, with no obligation and no fees. Want to learn more about our process? Visit our How It Works page, read real success stories, or contact us directly. You can also explore our blog for more helpful guides on selling your Arizona house fast.